Marin Fire Zones and Home Insurance: Where It’s Hardest to Insure, and What to Check Before You Buy
By Melissa DiVita, REALTOR®, Compass · DRE #01387955 · Fourth-generation Marin native, in real estate since 2003 · November 2026
The short answer: in Marin, the homes that are hardest and most expensive to insure are usually in a mapped High or Very High Fire Hazard Severity Zone, especially on wooded hillsides next to open space, and especially if they have an older wood shake roof. Before you write an offer, look up the property on the state’s 2025 fire hazard maps and get a real insurance quote. On one of my sales on Belvedere Island, the insurance came to about $25,000 a year, and the insurer required part of the shake roof to be replaced within 30 days of closing.
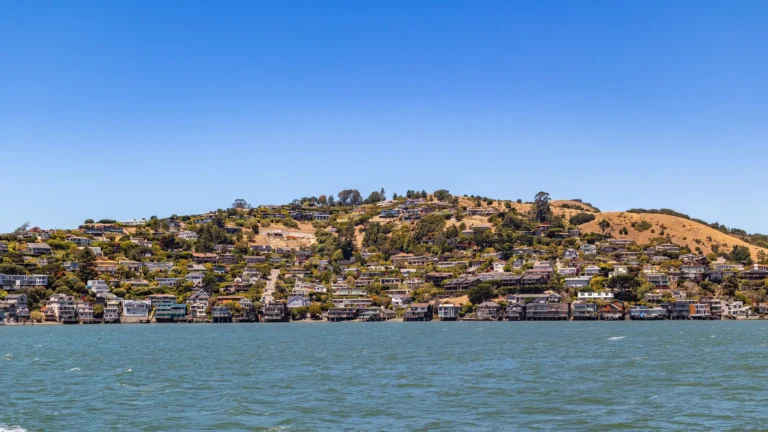
A Belvedere Island story
Here’s a real example from one of my sales on Belvedere Island. The buyers found coverage, but the premium was about $25,000 a year. And the insurer made a condition: a section of the home’s wood shake roof had to be replaced within 30 days of closing.
That’s the reality in a lot of Marin today. It’s not just “can you get insurance?” It’s how much, and what the insurer will make you fix first. Wood shake roofs are a red flag for insurers. The California Department of Insurance notes that most roofs qualify as Class A fire-rated, but wood shake shingles do not. Belvedere’s building code also requires a Class A roof on new homes and whenever more than half of a roof is replaced within a year.
The lesson for buyers: find out what the insurer will require before you remove your contingencies, so a roof project doesn’t surprise you after closing.
How to look up a Marin home’s fire zone
California’s Fire Hazard Severity Zone maps rate areas as Moderate, High or Very High, based on vegetation, terrain and weather. New maps for cities and towns, called Local Responsibility Areas, were released in 2025, and Marin’s towns, fire agencies and the county adopted them that year. That means a lot of Marin homes were rated for the first time, or rated higher than before.
- Look it up yourself on the State Fire Marshal’s Fire Hazard Severity Zone map viewer (linked in the sources below). Type in the address.
- Check the Natural Hazard Disclosure report. Every seller provides one, and it says whether the home is in a Very High Fire Hazard Severity Zone or a state wildland fire area.
- Ask the local fire agency. Some Marin fire departments require inspections when a home sells, and they can tell you what applies to a specific street.
Remember that the maps measure hazard, the natural conditions around a home, not the home itself. Two houses in the same zone can be very different to insure depending on the roof, vents, siding and what’s planted next to them.
Where insurance is hardest in Marin
Rather than guess at a list of streets, here’s the pattern I see, and what the maps reflect:
- Homes on wooded hillsides and canyons next to open space, where the wildland meets the neighborhood. That describes a lot of Marin, from the hills above Mill Valley, Fairfax, San Anselmo and Ross to Lucas Valley, Novato and West Marin.
- Homes on narrow, winding roads with one way in and out.
- Older homes with wood shake roofs, open eaves or wood siding, wherever they are. Belvedere Island is surrounded by water and its power lines are underground, and the roof still made the difference.
Since 2024, Marin homeowners have reported cancellations and non-renewals, and fewer standard insurers are writing new policies in California. Many buyers in higher-risk areas end up with a non-admitted carrier or the California FAIR Plan plus a “wrap” policy for the rest of their coverage. My Marin homeowners insurance guide explains how that works. One big catch for Marin: the FAIR Plan tops out at $3 million per home, and that limit covers the house, other structures and your belongings combined. The basic FAIR Plan policy also covers only a few perils, like fire, lightning and smoke, which is why it’s usually paired with a “difference in conditions” wrap policy for things like water damage and liability. If your home would cost more than $3 million to rebuild, you’ll need extra coverage on top of the FAIR Plan, or a high-value policy from a non-admitted insurer. Ask about this early, because it can add real cost.
Being underinsured is very common. Your coverage should be based on what it would cost to rebuild your home today, not what you paid for it or what it’s worth on the market. With inflation, rebuilding in Marin can run $1,000 a square foot or more. At that rate, a 3,000-square-foot home costs about $3 million to rebuild, which uses up the entire FAIR Plan limit before you’ve covered a single piece of furniture. Many policies were written years ago and never caught up. Ask your agent for a current rebuild-cost estimate, look for extended replacement cost coverage, and review your limits every year.
What insurers want to see
California’s “Safer from Wildfires” program lists home improvements that qualify for an insurance discount. They’re also a good checklist when you look at a house:
- A Class A fire-rated roof (wood shake doesn’t qualify)
- Ember-resistant vents with metal mesh
- At least 6 inches of noncombustible material at the base of exterior walls
- Enclosed eaves and multi-pane windows
- A 5-foot ember-resistant zone around the house: no plants or wood fencing right against it
- Clear space under decks, sheds moved at least 30 feet away, and defensible space that meets local rules
- Being in a Firewise USA community, which many Marin neighborhoods have joined
That 5-foot zone is about to become the law. In August 2026, the state Board of Forestry approved “Zone 0” rules limiting what can grow within 5 feet of homes in wildfire-prone areas. They apply right away to new construction and phase in for existing homes, with vegetation rules for existing homes starting in 2029 at the earliest.
Where the power lines are going underground
Overhead power lines are a known wildfire risk, and they’re behind the PG&E safety shutoffs that can cut power on windy days. PG&E’s plan for Marin County calls for 16 miles of undergrounding in 2026 and 2027, after about 1 mile completed through the end of 2025. Some Marin neighborhoods already have underground utilities. Belvedere Island is one: its power lines are underground. That’s worth knowing when you compare homes, but as my Belvedere Island sale shows, it doesn’t replace a fire-safe roof.
- Check a specific address on PG&E’s wildfire safety progress map, using the “Address Lookup” tab (linked below). It shows any undergrounding or line upgrades planned there.
- PG&E isn’t taking requests under this program. Neighborhoods that want lines buried can look at PG&E’s separate Rule 20 program, usually working through their town.
- Look up when you visit, too. You can see whether a street has overhead lines or not.
Why North Marin’s weather matters
I’ve written about how Marin’s microclimates change from town to town. Fire risk follows the same pattern. Southern Marin gets the summer fog. Novato and the north end of the county are warmer and drier, and they face the hills toward Sonoma.
- Diablo winds are hot, very dry winds from the northeast, usually in fall and winter, and Fire Safe Marin says they create extreme fire danger almost every year. In October 2017, during the North Bay fires, the Tubbs Fire burned to within 12 miles of Marin, and another fire skirted the Novato border.
- It’s getting warmer. A Washington Post analysis of NOAA data found Marin has warmed about 1.3°C since the late 1800s, faster than the U.S. average.
- Dry west winds are expected more often. Marin’s latest wildfire plan added a new scenario: ocean winds that arrive dry instead of foggy, combined with very dry vegetation and stronger winds, which it says are expected to happen more often.
My checklist for buyers
- Look up the fire zone before you fall in love with the house.
- Get an insurance quote early, ask what the insurer will require you to fix, and make sure the coverage matches today’s rebuild cost, not the purchase price.
- Check the roof: material, age and whether it’s Class A.
- Ask the seller about past insurance cancellations, fire inspections and defensible-space work.
- Don’t remove your contingencies until insurance is lined up. Your lender won’t fund the loan without it.
- Budget for hardening: vents, a roof, a cleared 5-foot zone. It can lower your premium and make the home easier to sell later.
Quick answers
How do I find out if a Marin home is in a high fire zone?
Look up the address on the State Fire Marshal’s Fire Hazard Severity Zone map viewer, which includes the 2025 maps Marin adopted for its cities and towns. The seller’s Natural Hazard Disclosure report also says whether the home is in a Very High Fire Hazard Severity Zone.
Can you insure a home with a wood shake roof in Marin?
Sometimes, but it’s harder and more expensive. Wood shake doesn’t count as a Class A fire-rated roof, and insurers may require replacing it. In one Belvedere Island sale, the insurer required part of the shake roof to be replaced within 30 days of closing.
Is PG&E burying power lines in Marin?
Yes. PG&E plans 16 miles of undergrounding in Marin County in 2026 and 2027. You can check a specific address on PG&E’s wildfire safety progress map.
Sources
- State Fire Marshal: Fire Hazard Severity Zone maps and viewer
- Marin County Fire: Fire Hazard Severity Zones
- California Department of Insurance: Safer from Wildfires
- Belvedere Municipal Code 16.04.030 (Class A roofing)
- NPR: California passes Zone 0 rules (August 2026)
- PG&E: undergrounding and system upgrades in Marin County
- Fire Safe Marin: understanding fire weather
- Fire Safe Marin: the 2017 North Bay fires and Marin
- Patch: how fast Marin County’s temperature is rising (NOAA data)
- United Policyholders / Marin IJ: Marin homeowners grapple with insurance cancellations
About the author: Melissa DiVita grew up in Belvedere, her family has been in Marin for four generations, and she lives in Tiburon. She has been a REALTOR® since 2003 and works with Compass in Tiburon. This is general information, not insurance advice. Talk to a licensed insurance agent about a specific property.
Looking at a house and worried about insurance? Send me a note. I’ll tell you what I know about the area and help you line up quotes before you write an offer.